How to Borrow Against Your Bitcoin Without Selling It

| KEY TAKEAWAYS: |
| — Borrowing against your Bitcoin means using your BTC as collateral to take out a loan you repay later, without selling the underlying Bitcoin. — Crypto-backed loans are governed by a loan-to-value (LTV) ratio and a health factor, and if your collateral drops too far in value, the protocol can liquidate it automatically. — Where you borrow decides who controls your collateral: a centralized platform holds it, while a self-custodial path like using the Ledger Wallet™ app with a Ledger signer keeps it under your control. |
Borrowing against your Bitcoin lets you raise cash without selling it. You pledge your BTC as collateral, draw a loan against its value, usually in stablecoins, and repay later to get your collateral back. The Bitcoin stays yours the whole time. The loan simply runs against it.
Collateral’s value determines how much you can borrow, and if its price falls too far, the protocol can sell it automatically to repay what you owe (this is called liquidation and is further explained below). Just as important is who holds that collateral while the loan is open, because that decides how much control you keep over it.
This guide walks through how crypto-backed loans work, the numbers that decide how much you can borrow, when a position gets liquidated, the risks worth weighing, and where you can borrow, from centralized exchanges to a self-custodial setup.
DISCLAIMER: This article is for informational and educational purposes only and does not constitute financial advice. Ledger is a technology provider and does not provide financial or investment recommendations. Crypto Loan is powered by Morpho and integrated via Yield.xyz. Subject to country availability. Interest rates are set by the interest rate model within the specific Morpho Blue Markets, and are determined by the markets’ underlying utilization rates. Liquidation risks apply.
What Does It Mean to Borrow Against Your Bitcoin?
Borrowing against your Bitcoin means using your BTC as collateral to take out a loan you repay later, without selling the underlying Bitcoin. The loan is usually paid out in a stablecoin, though what you can borrow depends on the platform.
When you sell Bitcoin, ownership transfers and the sale is final. When you pledge it as collateral, you keep ownership and borrow against its value instead, so your exposure to Bitcoin’s price stays intact.
The loan is enforced by code, not by a bank. A smart contract holds your collateral, tracks the loan in real time, and releases it when you repay. If your collateral’s value falls too far, the same contract sells enough of it to cover the debt.
How Do Crypto-Backed Loans Work?
Collateral is the asset you pledge to back a loan. If you fail to repay, that asset can be sold to cover what you owe.
Crypto-backed loans work through over-collateralization. You deposit more value than you borrow, and the protocol holds your collateral until you repay. That buffer is what protects the lender if prices move against you.
Four mechanics drive everything that happens next: how much you can borrow against your collateral (LTV), how close your position sits to a forced sale (health factor), what actually triggers that automatic and forced sale (liquidation), and how interest and repayment behave over the life of the loan.
Loan-to-Value (LTV)
Loan-to-value (LTV) measures how much you have borrowed against the value of your collateral. Put up $80,000 of Bitcoin and draw a $32,000 loan, and your LTV is 40%.
That one number sets the shape of the whole loan. A low LTV means less cash now but a wide gap before liquidation. A high LTV means more cash upfront and a thinner margin for error. The question it really answers is how far Bitcoin can fall before your position is forced into a sale.
Liquidation triggers when your rising LTV meets the protocol’s threshold, often around 86% for Bitcoin markets. Working back from that line shows what each starting point actually buys you on an $80,000 Bitcoin collateral:
| Starting LTV | Borrowed | How far BTC can fall before liquidation |
| 30% | $24,000 | about 65% |
| 50% | $40,000 | about 42% |
| 70% | $56,000 | about 19% |
The takeaway is in the gap between the rows. Moving from a 50% to a 70% LTV adds $16,000 of borrowing power, but it more than halves the drop your position can survive. That is why borrowers who plan to hold through volatility tend to start low and keep room to spare. Each protocol also sets its own maximum LTV for Bitcoin collateral, and that ceiling varies significantly from one platform to another.
Liquidation
Each protocol sets a liquidation threshold: the LTV at which your collateral gets sold automatically. It sits above the maximum you can borrow, giving your position some room before a forced sale.
Here is how the two numbers work together. Say a protocol liquidates at 86% LTV. If you start your loan at 50% LTV, Bitcoin would need to fall by roughly 42% before your position reaches that line.
When liquidation hits, the protocol sells enough collateral to repay the debt, plus a penalty fee.
Liquidations are automatic because of how on-chain lending works. The smart contract holding your collateral cannot verify your identity, contact you, or extend a grace period. If your loan goes underwater, the only way to guarantee lenders get repaid is to sell the collateral the moment it becomes unsafe.
Interest, Repayment, and Unwinding the Position
On most on-chain lending markets, interest rates are variable. They rise and fall with how much of the pool is being borrowed, so the rate you see at origination is not necessarily the rate you pay a month later.
There is usually no fixed end date. You can repay part or all of the loan whenever you want, as long as your position stays clear of its liquidation threshold. When you repay in full, the protocol releases your collateral and the position closes.
Why Borrow Against Bitcoin?
Selling Bitcoin to fund a short-term need carries a long-term cost: you give up any future upside on the coins you sold. A crypto-backed loan gives you liquidity while your stack stays intact, and you can unwind the position whenever it suits you.
Some long-term holders borrow against Bitcoin for a few main reasons.
- Preserving upside exposure. If you sell at $100,000 to cover an expense, you no longer benefit if BTC trades higher later. A loan keeps your stack in place.
- Funding real-life expenses. Home down payments, business capital, and large purchases are common uses. You cover the cost without unwinding a position you want to hold for years.
- Leverage and yield strategies. More active borrowers deposit BTC as collateral, borrow stablecoins, and redeploy them into more BTC, into yield-bearing positions, or into other on-chain strategies.
What Are the Risks of Borrowing Against Bitcoin?
Crypto-backed loans are a legitimate tool, but the risks are real and worth understanding before you deposit a single satoshi.
- Liquidation risk. Bitcoin moves fast, and a sharp drop can take a comfortable LTV to a liquidatable LTV in hours.
- Smart contract risk. Every on-chain loan depends on the underlying protocol’s smart contracts. Bugs, oracle failures, or exploits can affect your collateral even if you do everything right on your end.
- Custody risk on centralized platforms. Loans from centralized exchanges generally require you to transfer your Bitcoin into the exchange’s custody. Your collateral can be frozen, lost, or, in rare cases, rehypothecated, meaning used by the exchange in ways you never explicitly approved.
- Oracle and flash-crash risk. Lending protocols rely on price oracles. A brief mispricing or a flash crash can trigger liquidations that would not have happened under normal market conditions.
- Interest rate variability. Most on-chain rates are variable and respond to how heavily the pool is borrowed. The rate you start at can rise sharply if demand spikes.
None of these risks makes crypto-backed loans a bad idea. They are a tool that rewards careful position sizing and active monitoring.
Where Can You Borrow Against Bitcoin?
Three categories of platforms let you borrow against Bitcoin today. They differ less in their interest rates than in who actually controls your collateral during the life of the loan.
- Centralized exchanges (CEXs). Centralized exchanges run custodial loan products. The user experience is relatively seamless, but your Bitcoin sits in the exchange’s custody. You also face geographic restrictions, and your position is subject to account-level actions the exchange can take.
- DeFi protocols directly. Protocols like Morpho and Aave let you borrow against wrapped Bitcoin on-chain without giving up custody to a centralized counterparty. The user experience is fragmented, and most users access these protocols through software wallets, which keep your private keys on an internet-connected device.
- Hardware-secured self-custodial loans. The on-chain loan is initiated and managed natively from the Ledger Wallet app. Your private keys never leave the signer’s Secure Element chip, and every step of the loan is verified on the device’s Secure Screen before you approve it.
Each model has trade-offs.
| Custody model | Key control | Verification surface | Counterparty risk |
| CEX loan | Exchange holds collateral | Web or mobile app | High: exchange custody and operational risk |
| DeFi via software wallet | You hold keys (online) | Software wallet screen | Smart contract risk only |
| Hardware-secured self-custodial | You hold keys (offline) | Signer’s Secure Screen | Smart contract risk only |
Here is how borrowing works in the Ledger ecosystem, and why it keeps your collateral under your control from start to finish.
How to Borrow Against Bitcoin Via Ledger Wallet™
Ledger Wallet brings crypto-backed loans into the same app you already use to manage your portfolio, on desktop and mobile. There is no separate DeFi dashboard to learn and no third-party site to connect to. The liquidity comes from lenders in Morpho’s open credit network on Ethereum, and Yield.xyz provides the technical integration that connects the app to it.
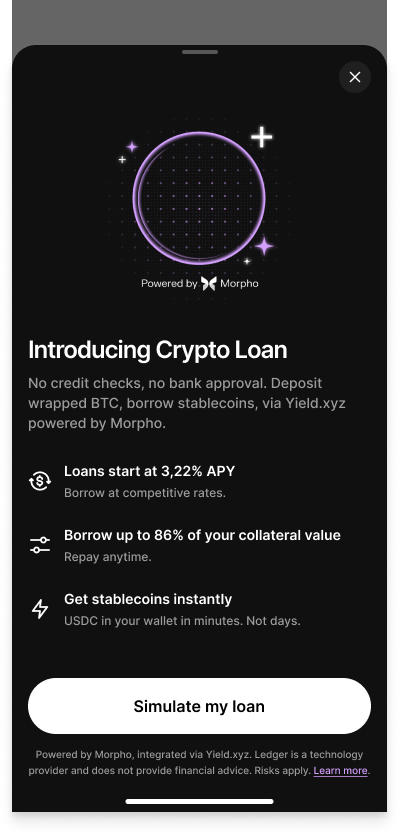
You deposit cbBTC or wBTC as collateral and borrow USDC or USDT against it. At launch, the integration supports four markets on Ethereum:
- cbBTC collateral, USDC loan
- cbBTC collateral, USDT loan
- wBTC collateral, USDC loan
- wBTC collateral, USDT loan
Why Borrow Against Bitcoin Via Ledger Wallet
- Keep your Bitcoin, unlock the liquidity. Borrowing against your wBTC or cbBTC raises spendable stablecoins without selling. Your Bitcoin exposure stays intact, and the liquidity is yours to fund a real-world cost or redeploy into other on-chain positions.
- Your collateral stays yours. On a custodial platform, your Bitcoin sits in a company’s wallet for the life of the loan, exposed to its solvency and to account-level actions like freezes. Here, your collateral stays on-chain and your keys stay offline on your Ledger signer. There is no counterparty holding your assets, and no account for anyone to freeze. However, the collateral is locked by the smart contract as security for the loan and will be liquidated automatically if the liquidation threshold is reached.
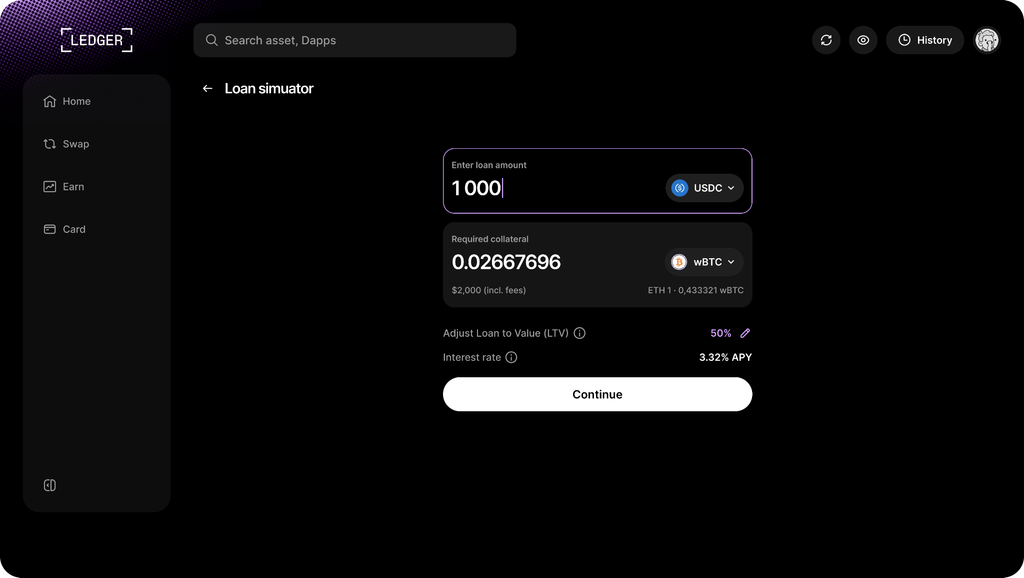
- Streamlined DeFi liquidity. The interface is built to be read at a glance, not decoded. You can see your loan-to-value and position health, then supply more collateral, repay, borrow more, or withdraw from the same screen, instead of stitching a loan together across separate DeFi tools.
The whole flow stays inside the app:
- Open Loans from the Ledger Wallet home screen.
- Choose your collateral and borrow pair, enter the amounts, and set your LTV to take on more or less risk.
- Clear Sign each required step, approving, supplying, and borrowing, on your Ledger signer.
- Track and manage the position from the same screen as your holdings.
Availability varies by region, so check the in-app eligibility for your location.
How Ledger Wallet™ Makes Borrowing Safer
The difference from a typical software-wallet DeFi loan comes down to where your keys live and what you see when you sign.
Your private keys stay on your Ledger signer’s Secure Element chip and stay isolated from the internet, which removes the remote attack surface that comes with hot wallets.
You can Clear Sign your transactions. Before you approve, the transaction is shown on the signer’s Secure Screen in plain, human-readable language, so you confirm what the contract will actually do instead of blind signing a screen a remote attacker could alter. Blind signing is not the default.
Nothing moves without your physical confirmation on the device. Approving the market, supplying collateral, borrowing, repaying, and withdrawing each require a press on the signer itself.
This is the integrated system at work. Ledger Wallet gives you the interface and the on-chain access, and the Ledger signer verifies every step. Security and usability stop being a trade-off.
Conclusion
Borrowing against your Bitcoin can be used as a financial tool. Used carefully, it lets you unlock liquidity without giving up the long-term position you are trying to build. Used carelessly, it exposes you to liquidation, smart contract risk, and interest costs you did not plan for.
The choice that matters most is not whether to borrow. It is where and how you do it. Ledger Wallet gives you the same on-chain access while keeping every confirmation on a screen no remote attacker can reach. When the signer verifies what the wallet displays, you keep both your liquidity and your control.
Frequently Asked Questions (FAQs)
Is Borrowing Against My Bitcoin Safer Than Selling?
These are two different decisions. Selling locks in your price and ends your exposure to Bitcoin. Borrowing keeps that exposure but adds liquidation risk and an interest cost. Which one fits depends entirely on what you are trying to achieve.
What Happens to My Bitcoin if Its Price Drops?
Your LTV rises and your health factor falls. If BTC drops far enough to push your LTV above the protocol’s liquidation threshold, the protocol automatically sells enough of your collateral to repay your debt, plus a liquidation penalty. You can prevent this by adding more collateral or repaying part of the loan before it triggers.
Do I Need to Wrap My Bitcoin to Borrow Against It?
Usually, yes. Native Bitcoin cannot be used directly as collateral on Ethereum-based lending protocols, so it is typically converted into a wrapped version such as wBTC or cbBTC, which are ERC-20 tokens backed 1:1 by BTC. Wrapping adds a custodian and a conversion step, so it is worth understanding what you are holding before you borrow.
Disclaimer: This article is informational, not tax advice. Tax treatment depends on where you live, how the loan is structured, and how the protocol handles collateral. Talk to a qualified tax professional before assuming any specific outcome.
Crypto Loan is powered by Morpho and integrated via Yield.xyz. Subject to country availability. Ledger is a technology provider and does not provide financial advice. Interest rates are variable and determined by the utilization of underlying isolated lending markets. Liquidation risks apply. Learn more here.
